Best Renters Insurance in California: 7 Things to Compare Before You Choose
Californians seeking renters insurance want coverage that meets their needs, fits within their budget, and accounts for the risks in their coverage area. Ranking websites do not pick the best renters insurance and company names do not show the winners. When comparing renters insurance coverage, do not assume that two renters with adjacent apartments in Tarzana will need the same coverage. Avoid the cheapest premium and the magazine's favorite. Smart shoppers compare the coverage based on the seven key criteria that determine if and how a claim will be paid.
This guide provides the California-specific coverage gaps that prevents renters from acquiring the coverage they need. After this guide, you will understand renters insurance quotes and what coverage you need.
Renters insurance has a low cost; however, understanding this insurance is not as simple. Many renters do not purchase the necessary coverage and assume their landlord's insurance policy covers their belongings (it does not). Many renters make the same mistake and obtain the cheapest coverage available. Avoiding these mistakes is not difficult and the payoff can eliminate a false sense of security.
Why “Best” Means Something Different for You
Most people want to choose the number one option on a “best carriers” list. Unfortunately, these types of lists do not consider your unique situation. A company’s ability to process claims for you as an individual is not listed. Your needs as a renter with a home office full of equipment are not the same as a renter who is a student with a laptop and bike. The risk evaluation is not the same for a renter who lives in a Valley neighborhood next to a wildfire as it is for a renter who lives downtown.
In this context, best = best fit, not best overall. The focus should be on which policy protects your belongings with the right limits, and a deductible that is within your means, and which you can trust to provide great service. The following seven factors address these key questions.
The 7 Things That Actually Matter
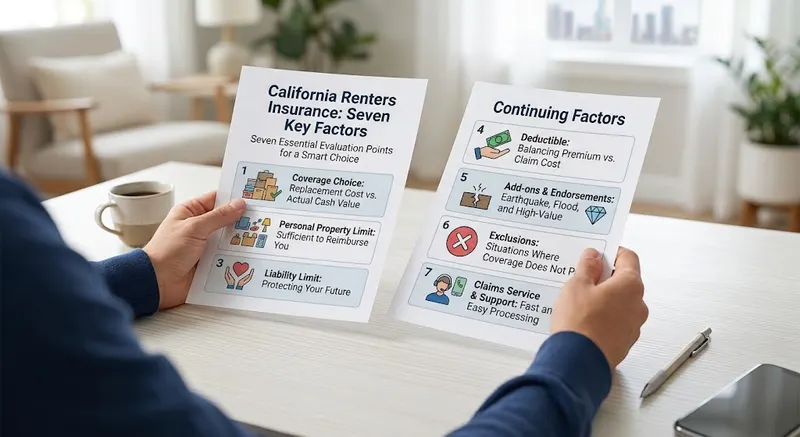
When you look at renters insurance in California, you should evaluate each quote against the seven items below. If a quote is disadvantageous in any of these areas, you could be underinsured, and may only realize that when you try to make a claim.
- 1 Coverage choice Replacement cost vs actual cash value. This one selection more than anything else, determines what your claim check amounts to.
- 2 Personal Property Limit The most an insurer will reimburse you for your personal property. If it’s too small, you’ll have to self-insure the difference.
- 3 Liability Limit Protects you if someone is injured in your unit or you damage someone’s property. Higher limits are only marginally more expensive.
- 4 Deductible The amount you agree to pay before coverage begins. A higher deductible means a lower premium, but it means more you pay when you make a claim.
- 5 Add-ons and endorsements Additional coverage for earthquakes, floods, and high-value items which are generally excluded from a basic policy.
- 6 Exclusions The situations where the policy will not pay. You will avoid unwelcome surprises if you read these.
- 7 Claims service and support The company's and agent's efforts to simplify the claims process for you..
Replacement cost vs. actual cash value
This section is important enough to and deserves its own section. If you have a replacement cost policy, you receive a new item. If you have an actual cash value policy, you receive a used item. So, let’s say you have a five-year-old couch that burned in a fire, with the former you would receive a brand new couch. With the latter, you would receive a used couch. For most people, replacement cost is the way to go.
Replacement Cost (RCV)
Replaces with new itemsSmall price difference, better payoutBest option for most renters
Actual Cash Value (ACV)
Pays used value less depreciationSmall price difference, less payoutMore cost effective for budget renters
Liability and add-ons
Liability coverage is the most important part of renters insurance. It pays for lawsuits when someone gets injured in your apartment or if you damage someone else's belongings. In this situation, the addition of liability coverage is worth the cost. Add-ons are additional coverage options you can purchase to protect yourself against lawsuits, and in California, these options typically include earthquake and flood coverage, along with a few specific endorsement policies for expensive jewelry and other items, musical instruments, and cameras.
Coverage for a Standard California Renters Policy
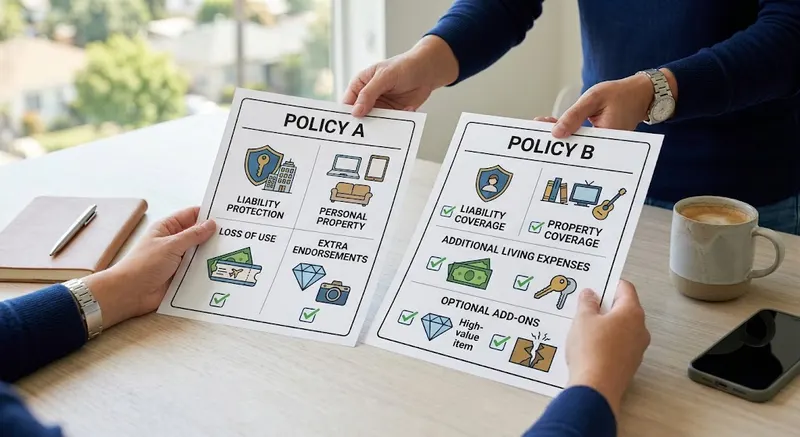
Standard renters insurance is broken into three sections and outlines the extent of coverage if you have to make a claim. Understanding each of these sections will allow you to understand the seven comparison criteria and help you faster compare coverage and price across insurance providers.
These three sections cover the basics of a standard renters insurance policy. Most providers standardize sections of their policy by limits, whether the loss is reimbursed at actual cash value or up to a set dollar amount for the property, and the list of perils that aren’t covered.
- Property: This section of your coverage reimburses you for your personal possessions if they are damaged by a covered peril, such as theft, fire, or vandalism. Damages due to burst pipes or water damage may also be covered.
- Liability: This section helps pays for legal costs related to someone being injured in your unit or damage that you caused to someone else’s property.
- Loss of Use: If you have to move out of your home due to a covered claim loss, this section of coverage reimburses you for the cost of a hotel or other covered living expenses.
Common Coverage Gaps in California Renters Insurance
Most standard renters insurance policies in CA have two major coverage gaps. Becoming aware of these gaps will help you understand the difference between having coverage and having no coverage.
If you want to examine the quake question more, our companion guide to earthquake coverage gaps will show how renters close that gap in California.
- Earthquakes: Standard renters policies will not cover damage caused by earthquakes in California. This must be covered by a separate endorsement or by the California Earthquake Authority. This is important to consider for anyone that resides in the San Fernando Valley, where earthquake activity is especially high.
- Floods: Like most standard policies, coverage for flood damage will need to be provided by a separate policy and should be considered depending on your location.
- High-value items: Much like other valuables, expensive jewelry, electronics and collectibles, may require a scheduled endorsement for complete coverage as their value often exceeds the standard limits for coverage per category.
Pitfalls When Selecting A Policy
Cautious renters will still make some of the same mistakes when it comes to insurance policy selection. These are the most frequent.
What can be done to avoid the mistakes listed? Make certain that a comparison of insurance plans is done in full so the price quoted is not the determining factor. A seemingly more affordable quote can result in higher premium when a claim is filed.
- Not enough coverage for personal belongings: Setting an unnecessarily low limit for personal property coverage in order to save a small amount in underwriting, only to discover that limit will not cover the loss of personal property.
- Not enough coverage for personal belongings: Setting an unnecessarily low limit for personal property coverage in order to save a small amount in underwriting, only to discover that limit will not cover the loss of personal property.
- Skimping on liability coverage: Setting the liability coverage limit to the minimum, when it can be increased for a small additional premium.
A Local Licensed Agent Helps You Compare
What value does a California licensed agent bring? Instead of making potential clients fill out dozens of forms on aggregator sites/apps, our independent agents are able to cross from one row to another, translate terms, and explain the coverage gaps and areas of importance. Our independent agents help potential clients understand the different coverages and limits and how they would fit in the client’s financial allocation, no insurance pressure sale. Visit our renters insurance page in California to learn more about the costs of our insurance, or follow our renters insurance comparison guide to better understand how to save. Beginning renters may find our renters first time guide helpful. If you drive, ask us about our discounted bundle of renters and auto insurance.
Are you ready to do a comparison the right way? Talk to a licensed California agent and let them ensure you are not insuring a name on a list.
FAQ
When buying renters insurance, what should I consider?
Consider the coverage, the limit on personal property, the liability limit, the deductible, and additional coverages, exclusions, and the quality of claims service. An insurance policy that has a favorable balance in all of the categories is arguably the best policy.
Is the least expensive renters insurance the best option?
Generally, no. The least expensive renters insurance is generally an actual cash value renters insurance policy that contains several exclusions and has a high deductible. Ultimately, the least expensive renters insurance can end up costing you much more when you have a claim, so examine the entire policy, not just the monthly cost.
How does replacement cost differ from actual cash value?
Replacement cost coverage is the cost to replace your property with new property, whereas actual cash value coverage is what the property is worth after it has been depreciated. Replacement cost coverage is generally more expensive, but it much better coverage and most renters cover this.
What coverage do most California renters overlook?
Coverage for floods and earthquakes are excluded in most standard policies. Also, coverage for high value items, jewelry and electronics for example, can exceed standard limits.
Should I have earthquake coverage as a renter in California?
No standard renters policies include this coverage. California has many active fault lines and earthquakes. Depending on what you own and how much risk you are willing to take, you should have this coverage.
How much liability coverage should a renter have?
Choose a limit that you think offers adequate financial protection in the event that someone is injured due to a misstep of your own or damage is caused to another unit due to your negligence. Since liability limits are inexpensive to raise, most renters opt for coverage that exceeds the bare minimum legal requirement.
Can I bundle renters insurance with car insurance in California?
You can, and by bundling your renters and auto you may find the price for both to be lower. A licensed agent can do a side-by-side pricing comparison for you, to demonstrate the savings that may be available to you for purchasing a bundle as compared to separate policies.