How Much Does Renters Insurance Cost in California in 2026? Factors Analyzed
How much is renters insurance in California? You're probably not going to like the answer, but we'll be honest. Renters insurance in California is actually pretty cheap, usually less than $10 per month for most people.
The problem with that answer? It's not a personal quote. Insurers calculate your quote with your personal information, the insurance limits you choose, and where you live.
Unfortunately, there is no average renters insurance price for California. Instead, you'll have to understand what factors have the greatest effect on the price of your insurance.
California Renters Insurance Cost and Factors
Renters insurance costs the same as all insurance policies; your price is your risk. The less you choose to insure against, the cheaper your renters insurance policy will be; however, if there is potential to cause more serious financial damages, your rates will be higher.
But what is a typical price for renters insurance in California?
The Difference Between Renters Insurance vs Homeowners Insurance
What makes renters insurance so much cheaper than homeowners insurance? Renters insurance does not include liability coverage for the dwelling, just your property, and also any injuries you may cause on the premises.
Why Your Quote Isn't Average
Generally, the numbers you see online are averages of many types of renters, big and small. They combine the price of a studio in Fresno with that of a three-bedroom in Los Angeles.
Your number is dependent on your ZIP code, how much personal property you’re insuring, and your deductible. Two neighbors can pay different amounts for the same reason two drivers pay different auto rates.
Thus, a real quote is ultimately better than a generalized number. The California Department of Insurance only publishes market information. To see your actual market, you must get a real quote.
The Things That Move Your Quote
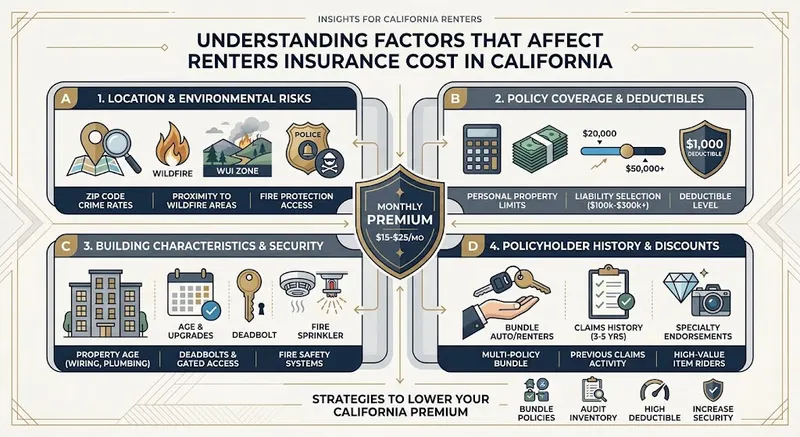
When it comes to pricing out your personal property, a few major factors come into play. Once you learn about these, you'll be able to understand your personal property quote.
Coverage Amount and Deductible
Your personal property coverage limit has the biggest impact on your premium. The more coverage you want, the more it costs.Your deductible has the opposite effect. A higher deductible means you’d pay more before insurance pays out on a claim, but each month it would lower your premium.The trade-off is obvious: a higher deductible means you pay more, but your premium is cheaper.
Zip Code and Risk
Your ZIP code has a lot to do with your premium. You’re assigned a risk rating based on how frequently claims are made in the area, the crime rate, and how active the weather is.An apartment in a busy neighborhood (like the San Fernando Valley) has a different risk rating than an apartment in a quiet area out by the suburbs. Having on-site security (or an updated building) can change your risk rating as well.
Your Coverage History and Selection
Choices you made in the past can affect pricing. We will now discuss selection of replacement cost versus actual cash value for your personal belongings.
Replacement Cost vs Actual Cash Value
This single decision determines your premium and your payout.Actual Cash Value (ACV) pays for the item’s present value after depreciation. Your five-year-old laptop would be valued at five years old and be reimbursed for the value of a five-year-old laptop.Replacement cost pays for what it costs to buy the item brand new. This premium is a small increase, but the payout after a loss is much greater.For most renters, the replacement cost is worth the small price difference.
What a Standard California Renters Policy Covers
A standard renters policy is an HO-4 policy. This combines a few basic protections into a single, cost-effective policy.
Personal Property Coverage
Covers theft or loss of your belongings due to a covered event as well as damage to your belongings. This protection covers your belongings, even when you are away from your residence.
Liability Coverage
Covers the cost of legal defense and/or the cost of a settlement if you are sued as the result of bodily injury to another party caused by you. It also covers the cost of damages you caused to someone else's property.
Additional Living Expenses
This covers the cost of lodging and related incidental costs if a covered event causes your residence to be uninhabitable. This is one of the least appreciated aspects of the policy.
How Add-ons Impact Your Costs
The primary insurance policy covers most but not all scenarios. A few add-ons can increase costs for more coverage.
Earthquake Insurance
Damage from earthquakes is not covered by typical renters insurance, and in some states like California, that is actually a major issue.You'll need to purchase an endorsement for an additional cost to cover this. To learn more, check out our article on renters insurance coverage for earthquakes.
Flood Insurance
Standard insurance policies also do not cover damage or loss from flooding. The necessity of this coverage does vary by location.
High-Value Possession Coverage
There are caps for the payouts on jewelry, art, and other collectibles and high-value items. To increase these coverage limits, a high-value item endorsement can be purchased.
How to Lower the Cost of Renters Insurance
Not all cheap California renters insurance is like the other policies out there. There are ways to save without diminishing your coverage.
Combine Insurance Policies
The first discount most people earn is bundling renters insurance with auto insurance. Many insurers will discount both policies if you bundle them together.
Pick Your Deductible Wisely
Going with a higher deductible will lead to a decrease in your insurance cost every month.
Ask About Discounts
Discounts for renters insurance abound if you have a security system or smoke detectors, and if you have a history of no claims.
Compare Prices
Different companies will price the exact same coverage differently, and knowing how to compare quotes can help you get the best coverage for the best price.
Common Misconceptions About Renters Insurance
These are common myths that keep people in California from purchasing renters insurance:
“My landlord’s insurance covers me.”
This is false. Your landlord’s insurance covers them, not you. If there is a break in, a burst pipe, or any other incident, you are responsible for your things....and that's what renters insurance is for.
“It’s too expensive for what it does.”
The truth is most people underestimate the coverage of renters insurance and how much it costs. What renters insurance provides, protecting your things and covering you financially in a loss, far outweighs what it costs.
“I don’t own enough to insure.”
Most people own things that, if they were to lose them, they would want to replace. Consider how much your stuff is worth...furniture, clothes, kitchen items, electronics.
“I can’t afford it.”
One of the biggest myths is that renters insurance is expensive. Though the truth is that it is typically one of the more inexpensive policies, where the coverage is one of the largest.
What Renters Insurance Does Not Cover
Knowing the gaps in coverage is as important as knowing the coverage. A standard HO-4 policy has clear limits.
Excluded Events
A typical renters insurance policy does not protect you from loss caused by floods or earthquakes. To have either of these determined events insured, you must buy a separate policy or endorse your current policy to add the coverage.Pest damage and wear and tear on your things are also not covered.
Coverage Caps on Specific Items
While wallets and jewelry have a high cash value, most renters insurance policies put a dollar limit on how much they will pay out.By knowing all of the above gaps, you will never be surprised by a lack of coverage.
Easy Access to Renters Insurance Quotes in California
At the end of the day, an average only tells you about a neighborhood, while an actual quote informs you how much it will cost you.
A licensed agent will be able to provide you with a quote because they can assess your personal property, your ZIP code, and your coverage goals. That will be exponentially more useful than what you will find online.
If you are renting in any location within the state of California, including Tarzana, Woodland Hills, Northridge, or North Hollywood, then the team at Online General Insurance are the folks to help you out. First-time renters should check out our guide to renters insurance in North Hollywood.
To see some real numbers, get a renters insurance quote in California made just for you. There are no more guessing games, and no pressure.
Frequently Asked Questions
How much is renters insurance per month in California?
The cost of renters insurance in California is case-dependent and can vary, but in general, policies for renters insurance in CA tend to be some of the least expensive options.Factors such as your coverage limits and your deductible can impact your costs. Your location is important too. To get an accurate quote, go ahead and fill one out to see how much renters insurance will cost you in California.
What contributes to one of the higher costs of renters insurance?
Factors such as the personal property and adding on insurance for high value or earthquake, ZIP codes that pose a high risk, and the deductible all impact the cost of your policy. So does the amount you’ve claimed in the past.
Does renters insurance take care of damage from earthquakes in California?
Unfortunately, standard coverage for renters’ insurance policies in CA do not address damage from earthquakes. However, because quakes do occur in California, the endorsement for earthquake is worth the investment to add on for your policy.
Are there ways to lower my renters insurance policy premium?
Absolutely. One way to is to raise your deductible. See what carriers can offer you in terms of discounts. Renters insurance is also an area you can save on by bundling your insurance options (e.g. car insurance, etc.).
Is renters insurance legally required in California?
No. However, landlords may require it. Renters insurance tends to be a small price to pay for coverage that is recommended by most landlords and a policy that leasers should look into.
Does renters insurance cover my roommates’ belongings?
Unfortunately, roommates that are not listed on the insurance policy are not covered. It is highly recommended that roommates get their own insurance for their belongings and coverage for their liability.
How much insurance should I have for renting?
Liability and personal effects coverage. Start by making a list of what you own, and figure out what you need to cover your personal effects. Set a limit for liability that you are comfortable with. An agent can help.
Does renters insurance take care of water damage?
It depends on the circumstances. More often they deal with sudden damage like burst pipes. Water damage from gradual leaks or flooding from outside the property are considered gradual and are mostly not covered. You will need to purchase a separate policy for flooding.
Will my renters insurance help replace my stuff if it was stolen from my car?
Most likely yes. Your personal property is covered under a standard insurance policy, including theft, as long as you meet your deductible and stay within your policy limits.
How long does it take to purchase renters insurance in California?
Typically the same day. A licensed insurance agent will be able to quote you a policy quickly if you know what your limits are and what your deductible is. You are usually able to obtain an insurance policy prior to moving into a rented property.Online General Insurance provides numerous insurance types (i.e., renters, auto, home, life, and business) for their customers in California. This article provides informational overviews, and should not enable you to purchase insurance for the quoted amounts and coverages. To make a purchase and receive custom quotes, contact a licensed insurance agent.