Renters Insurance and California Earthquakes: What You Should Know
California has its share of natural hazards, and earthquakes are a real part of the mix whether you own your home or rent an apartment. Many renters are surprised to learn that their policies do not automatically provide coverage for earthquakes.
Do Renters Insurance Policies Cover Earthquakes?
Typically, your renters insurance policy will not cover damage to your things caused by an earthquake. That is why earthquake coverage is an important part of renters insurance in California and should be considered separately from your standard policy.
A policy designed for renters will cover many of the issues you could run into day to day. When it comes to your belongings being damaged by an earthquake, though, you will most likely need separate coverage.
Figuring this out before a loss is far easier than doing it after one.
The Short Answer: Not Usually
The insurance policy your landlord carries usually has nothing to do with the damage an earthquake might cause to your personal property.
A renters insurance policy, also called an HO4 policy, typically covers your personal belongings and provides other coverages for the risks the policy is designed to address.
The California Department of Insurance states that typical renters, homeowners, and condominium policies do not include coverage for losses caused by earthquakes. To cover those losses, you would need to purchase a separate policy.
An earthquake affects your landlord and you differently. If your personal property is damaged when an earthquake shakes your apartment, you cannot rely on your landlord's property insurance.
This is why tenants need to understand the basics of their renters insurance, along with any separate policy they may buy to protect themselves from the effects of an earthquake.
What Your Renters Insurance Covers
The earthquake exclusion does not make renters insurance unnecessary. It means the policy has limits you need to understand.
A standard renters insurance policy can protect a tenant's personal property from certain losses such as theft, certain types of fire or smoke damage, and other causes listed in the policy.
Many renters policies cover personal property, include personal liability protection, and cover additional living expenses if a covered loss leaves the rental unusable. Your policy may also contain other coverages not described here.
For residents of Tarzana, Woodland Hills, Northridge, North Hollywood, and other parts of the San Fernando Valley, the question should not simply be, “Do I have insurance?”
A more useful question is, “What does my policy cover, and what important losses are excluded?”
A review of your renters insurance policy in California should answer those questions and explain other important exceptions in your policy.
An Exception After an Earthquake
There is an important distinction between direct damage from an earthquake and damage caused by a covered event that follows an earthquake.
The California Department of Insurance states that losses from fire following an earthquake are usually covered by homeowners and renters insurance policies. Coverage for other incidents depends on the policy wording.
At the same time, a loss that happens after an earthquake is not automatically covered either.
If a loss occurs, contact your insurance company to see how it fits within your policy rather than assuming it is not covered.
Why the Earthquake Exclusion Matters for Renters
Many renters think earthquake insurance is only for homeowners. That is not true.
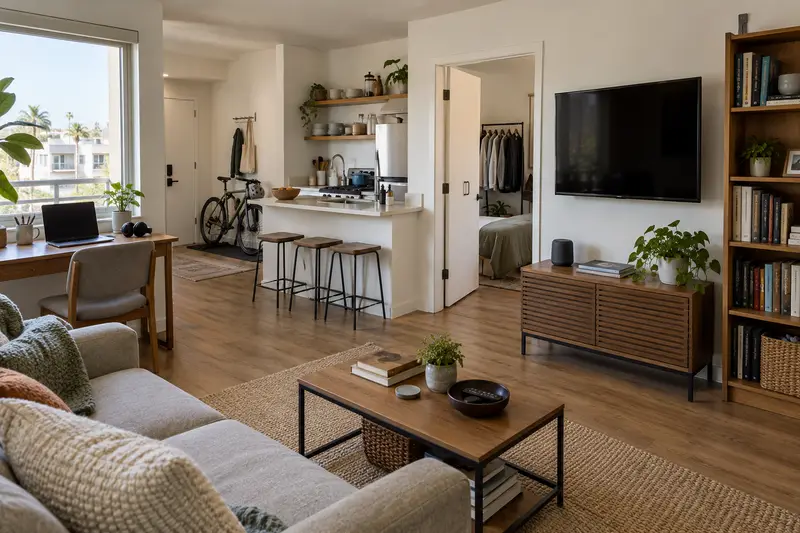
A renter's financial exposure can be significant, even though the renter does not own the building. Consider what you own inside your apartment:
- Laptops, televisions, furniture, clothing, kitchen appliances, bicycles, sports equipment, and other belongings can add up to far more than you might think.
- Replacing everything at the same time can easily create a significant out of pocket expense.
There is another concern. If an earthquake damages the building, your apartment may become unsafe to live in.Your landlord may repair the building, but that does not cover what you spend on temporary housing in the meantime.Earthquake insurance designed for renters may provide coverage for personal belongings and loss of use, which helps address that financial exposure.
How to Get Earthquake Coverage as a Renter in California
Just because something is not covered by your current policy does not mean coverage is unavailable.
Renters in California can buy protection for earthquake losses. It may be offered as standalone earthquake insurance from an insurance company, or through the California Earthquake Authority (CEA).
The CEA provides earthquake insurance to renters through its participating residential insurance companies. This coverage is purchased in addition to a standard renters policy.
Before you buy, look at the actual details of the policy and do not assume all policies are similar. Important points to consider include:
- How much personal property coverage is provided?
- What deductible applies?
- Is loss of use coverage included?
- Are there limits on the value of individual belongings?
- Are there any exclusions or special limits?
- What documentation would you need to provide after a loss?
Going through these questions with a licensed insurance agent can help you better understand the policy you are considering.
What Earthquake Insurance for Renters Covers
The coverage in your policy is what you have to go by. Two areas tend to matter most to renters: personal property and loss of use.
Personal Property
This coverage protects your belongings from losses caused by earthquakes.
Picture what it would take to replace everything in your apartment if an earthquake damaged it all. Your belongings are too important to guess at, so walk through each room and take stock:
- Furniture
- Computers and accessories
- Clothing
- Kitchenware
- Appliances
- Bicycles and sports equipment
- Work equipment
- Other belongings
That inventory can help you set a general range for how much coverage you may want.
Loss of Use
Even if you lose very few belongings, an earthquake could create safety concerns with the building itself and force you to move out for a while.
Loss of use coverage is designed to offset some of the extra costs of maintaining your usual standard of living while you cannot live in your home because of covered earthquake damage.
For many renters, loss of use is the most practical part of an earthquake policy. Replacing a chair is one thing. Paying for temporary lodging on top of your regular living expenses can be much harder to manage.
The CEA's current renters policy includes personal property and loss of use coverage, and its loss of use coverage has no deductible, which is not typical in the industry. Available limits and other policy terms should be reviewed at the time of purchase, because options are subject to change.
How Earthquake Deductibles Work
Earthquake coverage deserves its own review partly because earthquake deductibles can look quite different from standard renters policy deductibles.
For example, the CEA currently uses a percentage based deductible for renters personal property coverage, so you should understand what that percentage means in dollars based on the coverage limit you choose.
Do not choose coverage based only on the premium. Instead, ask:
If a covered earthquake loss happened tomorrow, how much would I receive after the deductible and policy limits are applied?
That question is a better indicator of how a policy would likely help you than the price alone.
The California Department of Insurance advises consumers to compare coverage, conditions, and available choices when shopping for residential insurance.
Does Your Landlord's Insurance Protect Your Belongings?
Typically, no.
The landlord insures their own interest in the property. A tenant needs their own insurance for personal property and personal liability.
Your claim is not covered just because the landlord has insurance. Renters insurance is essential, even if the property owner carries extensive coverage.
First time renters may find our North Hollywood renters insurance guide helpful. It describes other situations that can leave a renter exposed.
Is Earthquake Insurance Worth It for San Fernando Valley Renters?
There is no simple answer. You need to decide how much of a loss you could absorb on your own. Start with three questions.
First, how much property do you own? A furnished apartment and a sparsely furnished one do not carry the same exposure. Think about the actual cost to replace your belongings instead of assuming there is “not much” value in them.
Second, how would you pay for housing while you recover? What would your finances look like if you had to pay for somewhere else to stay for several days or weeks after an earthquake?
Third, how much financial risk are you willing to keep? When you buy earthquake insurance, you are choosing how much of the financial impact of an earthquake you will carry yourself and how much you want to transfer to an insurer.
Some renters buy earthquake insurance. Others decide on a different approach after looking at their savings, the cost of a policy, and other protections they may have. The goal is to evaluate the risk and make a deliberate decision.
Also keep in mind that earthquake insurance does not cover every related loss. If your car is damaged, for example, that claim would go through your auto policy instead.
Policy Reviews Should Focus on Cause of Loss, Property, and Coverage
A good policy review looks at the cause of loss, the property involved, and the specific coverage that applies.
The same event can cause several types of damage, and not all of it may be covered under a single insurance policy.
What Does Renters Earthquake Insurance Cost?
No single price applies to every California renter. The cost can vary based on the coverage amount, the deductible you choose, and other factors.
It is also important not to buy a policy simply because the price looks attractive. Compare what you are actually getting.
If you are already looking closely at what you pay for coverage, read our article on the cost of renters insurance in California. Then treat earthquake protection as a separate coverage decision.
Review Your Policy While You Can
It is much easier to read and understand your policy before you need to make a claim.
Open your declarations page and look at your personal property, liability, and loss of use coverage. Then look at the exclusions. If you do not have coverage for earthquake damage, ask what earthquake options are available to you.
This is also a good time to update your home inventory. Take photos or a video of your belongings and keep receipts for significant purchases. Store a backup copy somewhere outside your home in case you cannot get back in.
The purpose is simple: know what you own, know what your policy protects, and know where the coverage gaps are.
Adding Earthquake Protection to Your Renters Coverage
An earthquake exclusion in your renters policy does not mean you have to rebuild your entire insurance plan.
Begin by reviewing your renters insurance policy. Then evaluate earthquake insurance based on:
- Your estimate of your personal property value
- Available personal property limits
- Loss of use protection
- Deductibles
- Exclusions and special limits
If you have questions about any of these, ask for more details before you commit.
Review My Renters Coverage
Online General Insurance can help California renters understand what coverage they may need to protect against earthquake damage, without forcing the same coverage on everyone.
A review of your current renters insurance also shows where it already protects you and where separate earthquake coverage may be worth considering.
Frequently Asked Questions
Does standard renters insurance cover earthquake damage?
Most standard renters insurance policies do not cover losses caused by earth movement during an earthquake. Separate earthquake insurance policies are available for purchase. Coverage always depends on the specific policy and its exclusions.
How do renters get earthquake insurance in California?
Renters can contact their insurance agent or insurance company to find out whether coverage is available through an insurer that participates with the California Earthquake Authority, or through another available earthquake policy.
What can renters earthquake insurance cover?
It can cover personal property losses, as well as loss of use expenses if the rental becomes uninhabitable because of an earthquake. Limits, deductibles, and exclusions apply.
Does renters insurance cover a fire caused by an earthquake?
The California Department of Insurance says renters and homeowners policies usually cover losses from fire following an earthquake. Other losses that occur after an earthquake are decided case by case, so it is better to report the loss than to assume it is not covered.
Does my landlord's earthquake insurance cover my belongings?
A landlord's insurance does not pay for a renter's belongings. To protect your personal possessions, you need renters insurance, and you should review your options for earthquake coverage.
Is earthquake insurance worth having as a renter?
It depends on the value of your belongings, how much you have saved, how long you might need to stay somewhere else, the deductible, and how much coverage you can get. The premium should not be the only thing you look at.